
A business registered for GST that rents a shop, showroom, office or other non-residential premises from an owner who is not registered for GST has to pay the GST on that rent itself. The rule, known as reverse charge, has applied across India since 10 October 2024, and it covers Mohali, Zirakpur, Kharar and Dera Bassi in the same way.
It matters to both sides of a commercial lease. For the tenant, 18% of the rent becomes a tax it must deposit and report, even though the landlord's rent bill shows no tax at all. For an owner who is not registered, the rent stays the same, but a registered tenant now counts that tax as part of the cost of the premises.
Where the rule comes from
The GST Council recommended at its 54th meeting, on 9 September 2024, that renting of commercial property by an unregistered person to a registered person be brought under reverse charge to prevent revenue leakage.
Notification 09/2024-Central Tax (Rate), dated 8 October 2024, put this into effect from 10 October 2024. It added entry 5AB to the reverse charge list: renting of any property other than a residential dwelling, supplied by any unregistered person to any registered person. A corrigendum dated 22 October 2024 changed "any property" to "any immovable property".
The rate is 18%, split as 9% central GST and 9% state GST. Punjab State Transmission Corporation's tax circular of 10 October 2024, which told its own offices to pay the tax on non-residential premises rented from unregistered owners, records that rate and the service code 997212.
Who pays on a shop or office
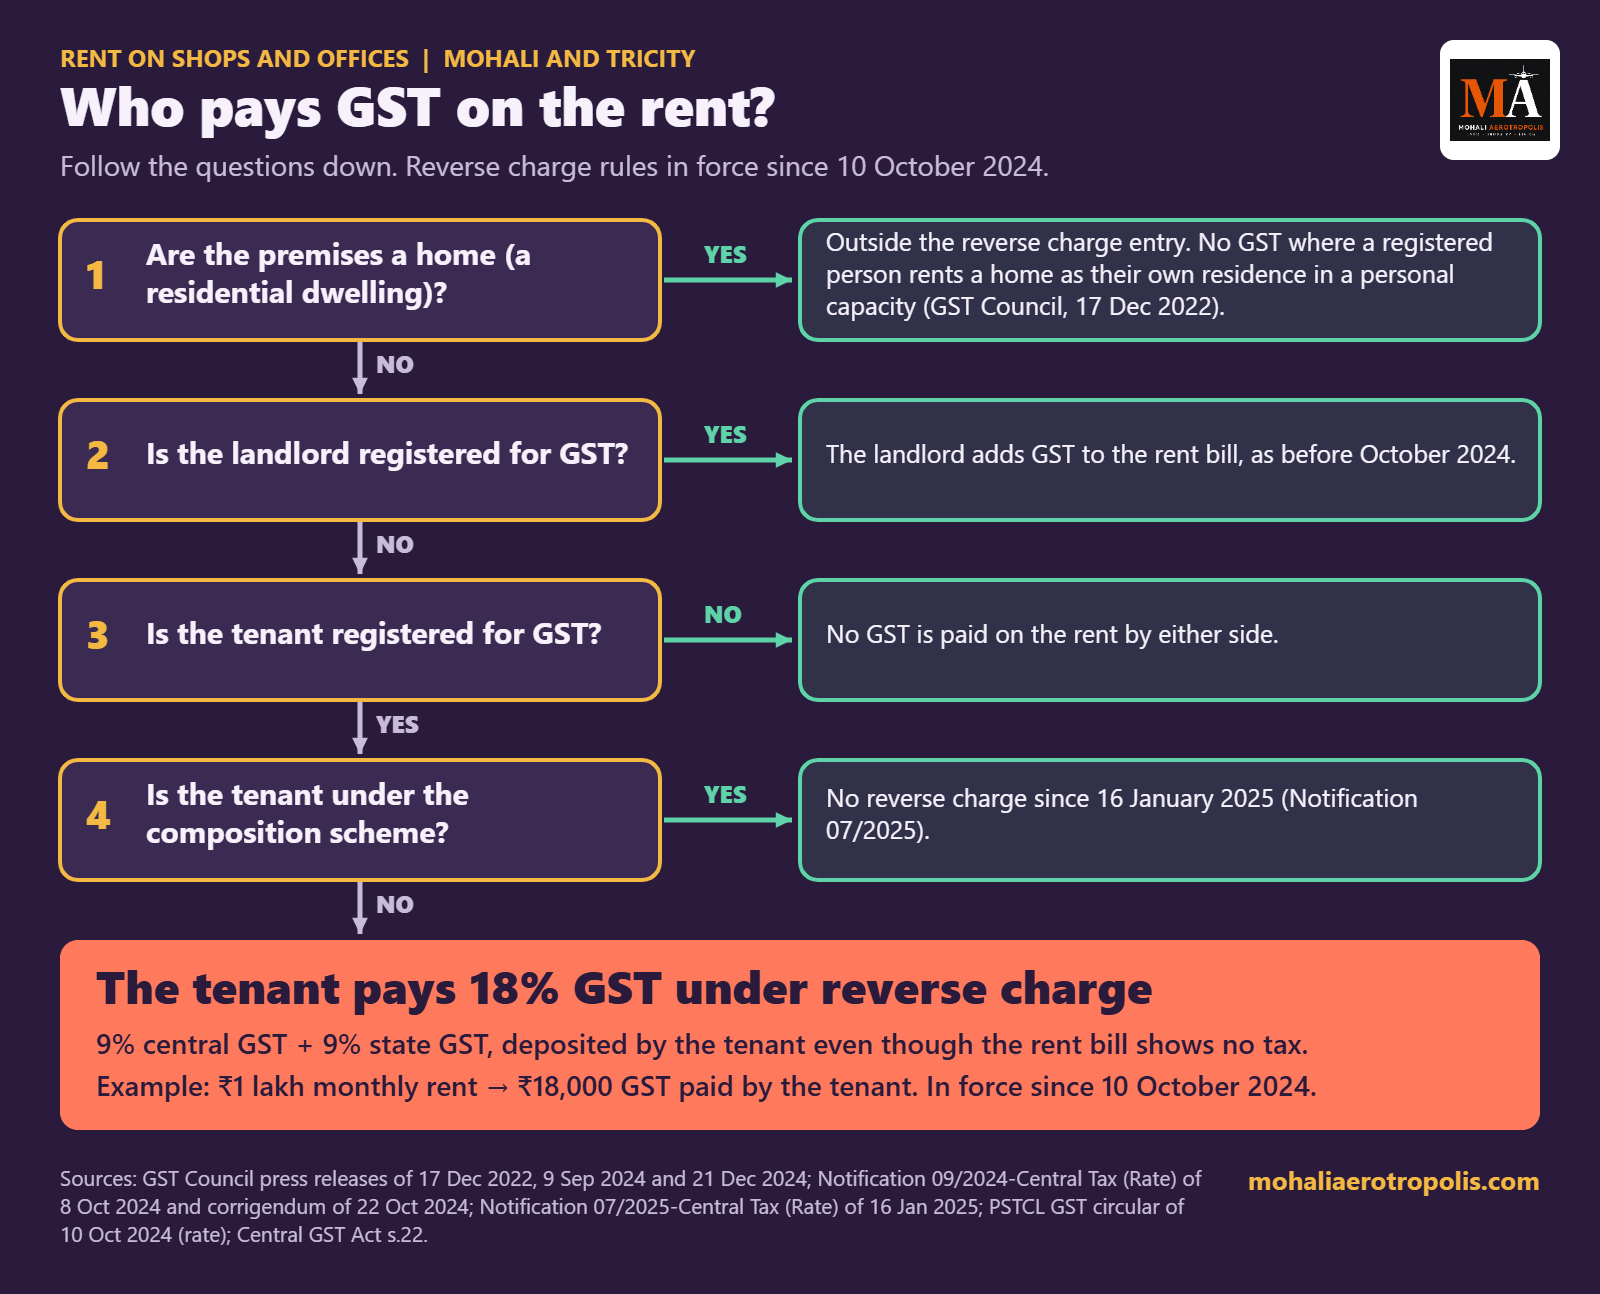
For non-residential premises, the answer turns on whether the landlord and the tenant are registered:
- Landlord registered: the landlord charges GST on the rent bill, as before October 2024.
- Landlord not registered, tenant registered: the tenant pays 18% under reverse charge.
- Landlord not registered, tenant under the composition scheme: no reverse charge since 16 January 2025.
- Landlord not registered, tenant not registered: no GST is paid on the rent.
Homes are a separate case
Entry 5AB leaves out residential dwellings. The GST Council also said on 17 December 2022 that no GST is payable where a residential dwelling is rented to a registered person who takes it in a personal capacity, for use as their own residence and not on account of the business.
Tenants under the composition scheme
The GST Council's 55th meeting, on 21 December 2024, recommended taking taxpayers under the composition levy out of entry 5AB. Notification 07/2025-Central Tax (Rate), dated 16 January 2025, did this by adding the words "other than a person who has opted to pay tax under composition levy" to the recipient column.
The Council also recommended regularising the period from 10 October 2024 until that notification on an "as is where is" basis. CBIC Circular 245/02/2025-GST covers the period from 10 October 2024 to 15 January 2025 for such tenants.
Who counts as unregistered
Section 22 of the Central GST Act requires a supplier to register once its aggregate turnover in a financial year exceeds ₹20 lakh. A lower limit of ₹10 lakh applies only in the special category states, and Punjab is not one of them. An owner below the limit who has not registered voluntarily is an unregistered supplier, and that is where reverse charge comes in.
Points to weigh
1. The quoted rent is not the whole cost. For a registered tenant renting from an unregistered owner, a monthly rent of ₹1 lakh carries ₹18,000 of GST, paid by the tenant.
2. Everything turns on the owner's registration. A GST number on the lease or the rent bill shows that the landlord charges the tax; its absence points to reverse charge for a registered tenant.
3. A flat taken by a business is not covered by entry 5AB. The December 2022 exemption, though, covers only a registered person renting a home as their own residence in a personal capacity.
4. Land and factory sheds raise questions. EY's tax alert of 14 October 2024 noted that the notification is wider than the Council's wording, which spoke only of commercial property, and that taxpayers may need to work out whether leases of industrial plots, factory buildings or commercial land fall within it.
Related reading
- Mohali Tenancy Rules Under the Punjab Rent Act
- Mohali Shops With Under 20 Workers Need Only an Intimation
- Mohali Flats Bought After Completion Carry No GST
Sources: The sources we use are listed on our Editorial Sources page.
This article explains how GST applies to rent on shops, offices and other premises in Mohali and the Tricity, based on sources read on 17 November 2026. It is general information, not tax, legal or business advice.
GST में पंजीकृत कोई कारोबार अगर ऐसे मालिक से दुकान, शोरूम, दफ़्तर या कोई और गैर-आवासीय परिसर किराये पर लेता है जो GST में पंजीकृत नहीं है, तो उस किराये पर GST उसे ख़ुद चुकाना होता है। रिवर्स चार्ज कहलाने वाला यह नियम 10 अक्टूबर 2024 से पूरे भारत में लागू है, और मोहाली, ज़ीरकपुर, खरड़ और डेराबस्सी पर भी उसी तरह लागू होता है।
यह व्यावसायिक लीज़ के दोनों पक्षों के लिए मायने रखता है। किरायेदार के लिए किराये का 18% ऐसा टैक्स बन जाता है जिसे उसे जमा करना और रिटर्न में दिखाना होता है, भले ही मकान मालिक के किराये के बिल में कोई टैक्स न हो। जो मालिक पंजीकृत नहीं है, उसका किराया वही रहता है, लेकिन पंजीकृत किरायेदार अब इस टैक्स को परिसर की लागत का हिस्सा मानता है।
नियम कहाँ से आया
GST काउंसिल ने 9 सितंबर 2024 को अपनी 54वीं बैठक में सिफ़ारिश की कि राजस्व के रिसाव को रोकने के लिए किसी अपंजीकृत व्यक्ति द्वारा पंजीकृत व्यक्ति को व्यावसायिक संपत्ति किराये पर देने को रिवर्स चार्ज के तहत लाया जाए।
8 अक्टूबर 2024 की अधिसूचना 09/2024-Central Tax (Rate) ने इसे 10 अक्टूबर 2024 से लागू किया। इसने रिवर्स चार्ज सूची में प्रविष्टि 5AB जोड़ी: आवासीय मकान (residential dwelling) के अलावा किसी भी संपत्ति को किराये पर देना, जहाँ आपूर्तिकर्ता कोई भी अपंजीकृत व्यक्ति हो और प्राप्तकर्ता कोई भी पंजीकृत व्यक्ति। 22 अक्टूबर 2024 के शुद्धिपत्र ने "any property" को बदलकर "any immovable property" कर दिया।
दर 18% है, जो 9% केंद्रीय GST और 9% राज्य GST में बँटी है। पंजाब स्टेट ट्रांसमिशन कॉरपोरेशन का 10 अक्टूबर 2024 का टैक्स सर्कुलर, जिसमें उसने अपने दफ़्तरों को अपंजीकृत मालिकों से किराये पर लिए गए गैर-आवासीय परिसरों पर टैक्स चुकाने को कहा, यही दर और सेवा कोड 997212 दर्ज करता है।
दुकान या दफ़्तर पर कौन चुकाता है
गैर-आवासीय परिसर के लिए जवाब इस पर टिका है कि मकान मालिक और किरायेदार पंजीकृत हैं या नहीं:
- मकान मालिक पंजीकृत: मकान मालिक किराये के बिल पर GST लगाता है, जैसा अक्टूबर 2024 से पहले होता था।
- मकान मालिक पंजीकृत नहीं, किरायेदार पंजीकृत: किरायेदार रिवर्स चार्ज के तहत 18% चुकाता है।
- मकान मालिक पंजीकृत नहीं, किरायेदार कंपोज़िशन स्कीम में: 16 जनवरी 2025 से कोई रिवर्स चार्ज नहीं।
- मकान मालिक पंजीकृत नहीं, किरायेदार पंजीकृत नहीं: किराये पर कोई GST नहीं चुकाया जाता।
घर अलग मामला हैं
प्रविष्टि 5AB आवासीय मकानों को बाहर रखती है। GST काउंसिल ने 17 दिसंबर 2022 को यह भी कहा था कि जहाँ कोई आवासीय मकान ऐसे पंजीकृत व्यक्ति को किराये पर दिया जाए जो उसे निजी हैसियत में, अपने रहने के लिए और कारोबार के खाते से नहीं, लेता है, वहाँ कोई GST देय नहीं है।
कंपोज़िशन स्कीम वाले किरायेदार
21 दिसंबर 2024 को GST काउंसिल की 55वीं बैठक ने सिफ़ारिश की कि कंपोज़िशन लेवी वाले करदाताओं को प्रविष्टि 5AB से बाहर किया जाए। 16 जनवरी 2025 की अधिसूचना 07/2025-Central Tax (Rate) ने प्राप्तकर्ता वाले कॉलम में "other than a person who has opted to pay tax under composition levy" शब्द जोड़कर यह किया।
काउंसिल ने 10 अक्टूबर 2024 से उस अधिसूचना तक की अवधि को "as is where is" आधार पर नियमित करने की भी सिफ़ारिश की। CBIC का सर्कुलर 245/02/2025-GST ऐसे किरायेदारों के लिए 10 अक्टूबर 2024 से 15 जनवरी 2025 तक की अवधि को कवर करता है।
अपंजीकृत किसे माना जाता है
केंद्रीय GST अधिनियम की धारा 22 के अनुसार किसी आपूर्तिकर्ता को तब पंजीकरण कराना होता है जब एक वित्तीय वर्ष में उसका कुल टर्नओवर ₹20 लाख से अधिक हो जाए। ₹10 लाख की कम सीमा केवल विशेष श्रेणी के राज्यों में लागू होती है, और पंजाब उनमें शामिल नहीं है। सीमा से नीचे का कोई मालिक, जिसने स्वेच्छा से पंजीकरण नहीं कराया, अपंजीकृत आपूर्तिकर्ता है, और यहीं से रिवर्स चार्ज लागू होता है।
ध्यान देने योग्य बातें
1. बताया गया किराया पूरी लागत नहीं है। अपंजीकृत मालिक से किराये पर लेने वाले पंजीकृत किरायेदार के लिए ₹1 लाख के मासिक किराये पर ₹18,000 का GST बनता है, जो किरायेदार चुकाता है।
2. सब कुछ मालिक के पंजीकरण पर टिका है। लीज़ या किराये के बिल पर GST नंबर दिखाता है कि मकान मालिक टैक्स लगाता है; उसका न होना पंजीकृत किरायेदार के लिए रिवर्स चार्ज की ओर इशारा करता है।
3. किसी कारोबार द्वारा लिया गया फ़्लैट प्रविष्टि 5AB में नहीं आता। लेकिन दिसंबर 2022 की छूट केवल उस पंजीकृत व्यक्ति पर लागू होती है जो घर निजी हैसियत में अपने रहने के लिए किराये पर लेता है।
4. ज़मीन और फ़ैक्टरी शेड पर सवाल उठते हैं। EY के 14 अक्टूबर 2024 के टैक्स अलर्ट में कहा गया कि अधिसूचना काउंसिल की शब्दावली से व्यापक है, जिसमें केवल व्यावसायिक संपत्ति की बात थी, और करदाताओं को यह तय करना पड़ सकता है कि औद्योगिक प्लॉट, फ़ैक्टरी भवन या व्यावसायिक ज़मीन की लीज़ इसके दायरे में आती है या नहीं।
संबंधित लेख
- Mohali Tenancy Rules Under the Punjab Rent Act
- Mohali Shops With Under 20 Workers Need Only an Intimation
- Mohali Flats Bought After Completion Carry No GST
स्रोत: हम जिन स्रोतों का उपयोग करते हैं, वे हमारे Editorial Sources पेज पर सूचीबद्ध हैं।
यह लेख बताता है कि मोहाली और ट्राइसिटी में दुकानों, दफ़्तरों और अन्य परिसरों के किराये पर GST कैसे लागू होता है, और 17 नवंबर 2026 को पढ़े गए स्रोतों पर आधारित है। यह सामान्य जानकारी है, टैक्स, कानूनी या व्यावसायिक सलाह नहीं।
GST ਵਿੱਚ ਰਜਿਸਟਰਡ ਕੋਈ ਕਾਰੋਬਾਰ ਜੇ ਅਜਿਹੇ ਮਾਲਕ ਤੋਂ ਦੁਕਾਨ, ਸ਼ੋਅਰੂਮ, ਦਫ਼ਤਰ ਜਾਂ ਕੋਈ ਹੋਰ ਗੈਰ-ਰਿਹਾਇਸ਼ੀ ਥਾਂ ਕਿਰਾਏ 'ਤੇ ਲੈਂਦਾ ਹੈ ਜੋ GST ਵਿੱਚ ਰਜਿਸਟਰਡ ਨਹੀਂ, ਤਾਂ ਉਸ ਕਿਰਾਏ 'ਤੇ GST ਉਸ ਨੂੰ ਖ਼ੁਦ ਭਰਨਾ ਪੈਂਦਾ ਹੈ। ਰਿਵਰਸ ਚਾਰਜ ਕਹਾਉਣ ਵਾਲਾ ਇਹ ਨਿਯਮ 10 ਅਕਤੂਬਰ 2024 ਤੋਂ ਪੂਰੇ ਭਾਰਤ ਵਿੱਚ ਲਾਗੂ ਹੈ, ਅਤੇ ਮੋਹਾਲੀ, ਜ਼ੀਰਕਪੁਰ, ਖਰੜ ਅਤੇ ਡੇਰਾਬੱਸੀ 'ਤੇ ਵੀ ਇਸੇ ਤਰ੍ਹਾਂ ਲਾਗੂ ਹੁੰਦਾ ਹੈ।
ਇਹ ਵਪਾਰਕ ਲੀਜ਼ ਦੀਆਂ ਦੋਵੇਂ ਧਿਰਾਂ ਲਈ ਮਾਇਨੇ ਰੱਖਦਾ ਹੈ। ਕਿਰਾਏਦਾਰ ਲਈ ਕਿਰਾਏ ਦਾ 18% ਅਜਿਹਾ ਟੈਕਸ ਬਣ ਜਾਂਦਾ ਹੈ ਜੋ ਉਸ ਨੂੰ ਜਮ੍ਹਾ ਕਰਨਾ ਅਤੇ ਰਿਟਰਨ ਵਿੱਚ ਦਿਖਾਉਣਾ ਪੈਂਦਾ ਹੈ, ਭਾਵੇਂ ਮਕਾਨ ਮਾਲਕ ਦੇ ਕਿਰਾਏ ਦੇ ਬਿੱਲ ਵਿੱਚ ਕੋਈ ਟੈਕਸ ਨਾ ਹੋਵੇ। ਜੋ ਮਾਲਕ ਰਜਿਸਟਰਡ ਨਹੀਂ, ਉਸ ਦਾ ਕਿਰਾਇਆ ਉਹੀ ਰਹਿੰਦਾ ਹੈ, ਪਰ ਰਜਿਸਟਰਡ ਕਿਰਾਏਦਾਰ ਹੁਣ ਇਸ ਟੈਕਸ ਨੂੰ ਥਾਂ ਦੀ ਲਾਗਤ ਦਾ ਹਿੱਸਾ ਗਿਣਦਾ ਹੈ।
ਨਿਯਮ ਕਿੱਥੋਂ ਆਇਆ
GST ਕੌਂਸਲ ਨੇ 9 ਸਤੰਬਰ 2024 ਨੂੰ ਆਪਣੀ 54ਵੀਂ ਮੀਟਿੰਗ ਵਿੱਚ ਸਿਫ਼ਾਰਸ਼ ਕੀਤੀ ਕਿ ਮਾਲੀਏ ਦੇ ਰਿਸਾਅ ਨੂੰ ਰੋਕਣ ਲਈ ਕਿਸੇ ਗੈਰ-ਰਜਿਸਟਰਡ ਵਿਅਕਤੀ ਵੱਲੋਂ ਰਜਿਸਟਰਡ ਵਿਅਕਤੀ ਨੂੰ ਵਪਾਰਕ ਜਾਇਦਾਦ ਕਿਰਾਏ 'ਤੇ ਦੇਣ ਨੂੰ ਰਿਵਰਸ ਚਾਰਜ ਹੇਠ ਲਿਆਂਦਾ ਜਾਵੇ।
8 ਅਕਤੂਬਰ 2024 ਦੀ ਨੋਟੀਫਿਕੇਸ਼ਨ 09/2024-Central Tax (Rate) ਨੇ ਇਸ ਨੂੰ 10 ਅਕਤੂਬਰ 2024 ਤੋਂ ਲਾਗੂ ਕੀਤਾ। ਇਸ ਨੇ ਰਿਵਰਸ ਚਾਰਜ ਸੂਚੀ ਵਿੱਚ ਐਂਟਰੀ 5AB ਜੋੜੀ: ਰਿਹਾਇਸ਼ੀ ਮਕਾਨ (residential dwelling) ਤੋਂ ਇਲਾਵਾ ਕਿਸੇ ਵੀ ਜਾਇਦਾਦ ਨੂੰ ਕਿਰਾਏ 'ਤੇ ਦੇਣਾ, ਜਿੱਥੇ ਸਪਲਾਇਰ ਕੋਈ ਵੀ ਗੈਰ-ਰਜਿਸਟਰਡ ਵਿਅਕਤੀ ਹੋਵੇ ਅਤੇ ਪ੍ਰਾਪਤਕਰਤਾ ਕੋਈ ਵੀ ਰਜਿਸਟਰਡ ਵਿਅਕਤੀ। 22 ਅਕਤੂਬਰ 2024 ਦੇ ਸੋਧ-ਪੱਤਰ ਨੇ "any property" ਨੂੰ ਬਦਲ ਕੇ "any immovable property" ਕਰ ਦਿੱਤਾ।
ਦਰ 18% ਹੈ, ਜੋ 9% ਕੇਂਦਰੀ GST ਅਤੇ 9% ਸੂਬਾਈ GST ਵਿੱਚ ਵੰਡੀ ਹੋਈ ਹੈ। ਪੰਜਾਬ ਸਟੇਟ ਟ੍ਰਾਂਸਮਿਸ਼ਨ ਕਾਰਪੋਰੇਸ਼ਨ ਦਾ 10 ਅਕਤੂਬਰ 2024 ਦਾ ਟੈਕਸ ਸਰਕੂਲਰ, ਜਿਸ ਵਿੱਚ ਉਸ ਨੇ ਆਪਣੇ ਦਫ਼ਤਰਾਂ ਨੂੰ ਗੈਰ-ਰਜਿਸਟਰਡ ਮਾਲਕਾਂ ਤੋਂ ਕਿਰਾਏ 'ਤੇ ਲਈਆਂ ਗੈਰ-ਰਿਹਾਇਸ਼ੀ ਥਾਵਾਂ 'ਤੇ ਟੈਕਸ ਭਰਨ ਲਈ ਕਿਹਾ, ਇਹੀ ਦਰ ਅਤੇ ਸੇਵਾ ਕੋਡ 997212 ਦਰਜ ਕਰਦਾ ਹੈ।
ਦੁਕਾਨ ਜਾਂ ਦਫ਼ਤਰ 'ਤੇ ਕੌਣ ਭਰਦਾ ਹੈ
ਗੈਰ-ਰਿਹਾਇਸ਼ੀ ਥਾਂ ਲਈ ਜਵਾਬ ਇਸ 'ਤੇ ਟਿਕਿਆ ਹੈ ਕਿ ਮਕਾਨ ਮਾਲਕ ਅਤੇ ਕਿਰਾਏਦਾਰ ਰਜਿਸਟਰਡ ਹਨ ਜਾਂ ਨਹੀਂ:
- ਮਕਾਨ ਮਾਲਕ ਰਜਿਸਟਰਡ: ਮਕਾਨ ਮਾਲਕ ਕਿਰਾਏ ਦੇ ਬਿੱਲ 'ਤੇ GST ਲਾਉਂਦਾ ਹੈ, ਜਿਵੇਂ ਅਕਤੂਬਰ 2024 ਤੋਂ ਪਹਿਲਾਂ ਹੁੰਦਾ ਸੀ।
- ਮਕਾਨ ਮਾਲਕ ਰਜਿਸਟਰਡ ਨਹੀਂ, ਕਿਰਾਏਦਾਰ ਰਜਿਸਟਰਡ: ਕਿਰਾਏਦਾਰ ਰਿਵਰਸ ਚਾਰਜ ਹੇਠ 18% ਭਰਦਾ ਹੈ।
- ਮਕਾਨ ਮਾਲਕ ਰਜਿਸਟਰਡ ਨਹੀਂ, ਕਿਰਾਏਦਾਰ ਕੰਪੋਜ਼ੀਸ਼ਨ ਸਕੀਮ ਵਿੱਚ: 16 ਜਨਵਰੀ 2025 ਤੋਂ ਕੋਈ ਰਿਵਰਸ ਚਾਰਜ ਨਹੀਂ।
- ਮਕਾਨ ਮਾਲਕ ਰਜਿਸਟਰਡ ਨਹੀਂ, ਕਿਰਾਏਦਾਰ ਰਜਿਸਟਰਡ ਨਹੀਂ: ਕਿਰਾਏ 'ਤੇ ਕੋਈ GST ਨਹੀਂ ਭਰਿਆ ਜਾਂਦਾ।
ਘਰ ਵੱਖਰਾ ਮਾਮਲਾ ਹਨ
ਐਂਟਰੀ 5AB ਰਿਹਾਇਸ਼ੀ ਮਕਾਨਾਂ ਨੂੰ ਬਾਹਰ ਰੱਖਦੀ ਹੈ। GST ਕੌਂਸਲ ਨੇ 17 ਦਸੰਬਰ 2022 ਨੂੰ ਇਹ ਵੀ ਕਿਹਾ ਸੀ ਕਿ ਜਿੱਥੇ ਕੋਈ ਰਿਹਾਇਸ਼ੀ ਮਕਾਨ ਅਜਿਹੇ ਰਜਿਸਟਰਡ ਵਿਅਕਤੀ ਨੂੰ ਕਿਰਾਏ 'ਤੇ ਦਿੱਤਾ ਜਾਵੇ ਜੋ ਉਸ ਨੂੰ ਨਿੱਜੀ ਹੈਸੀਅਤ ਵਿੱਚ, ਆਪਣੀ ਰਿਹਾਇਸ਼ ਲਈ ਅਤੇ ਕਾਰੋਬਾਰ ਦੇ ਖਾਤੇ ਤੋਂ ਨਹੀਂ, ਲੈਂਦਾ ਹੈ, ਉੱਥੇ ਕੋਈ GST ਨਹੀਂ ਬਣਦਾ।
ਕੰਪੋਜ਼ੀਸ਼ਨ ਸਕੀਮ ਵਾਲੇ ਕਿਰਾਏਦਾਰ
21 ਦਸੰਬਰ 2024 ਨੂੰ GST ਕੌਂਸਲ ਦੀ 55ਵੀਂ ਮੀਟਿੰਗ ਨੇ ਸਿਫ਼ਾਰਸ਼ ਕੀਤੀ ਕਿ ਕੰਪੋਜ਼ੀਸ਼ਨ ਲੇਵੀ ਵਾਲੇ ਕਰਦਾਤਾਵਾਂ ਨੂੰ ਐਂਟਰੀ 5AB ਤੋਂ ਬਾਹਰ ਕੀਤਾ ਜਾਵੇ। 16 ਜਨਵਰੀ 2025 ਦੀ ਨੋਟੀਫਿਕੇਸ਼ਨ 07/2025-Central Tax (Rate) ਨੇ ਪ੍ਰਾਪਤਕਰਤਾ ਵਾਲੇ ਕਾਲਮ ਵਿੱਚ "other than a person who has opted to pay tax under composition levy" ਸ਼ਬਦ ਜੋੜ ਕੇ ਇਹ ਕੀਤਾ।
ਕੌਂਸਲ ਨੇ 10 ਅਕਤੂਬਰ 2024 ਤੋਂ ਉਸ ਨੋਟੀਫਿਕੇਸ਼ਨ ਤੱਕ ਦੇ ਸਮੇਂ ਨੂੰ "as is where is" ਆਧਾਰ 'ਤੇ ਨਿਯਮਿਤ ਕਰਨ ਦੀ ਵੀ ਸਿਫ਼ਾਰਸ਼ ਕੀਤੀ। CBIC ਦਾ ਸਰਕੂਲਰ 245/02/2025-GST ਅਜਿਹੇ ਕਿਰਾਏਦਾਰਾਂ ਲਈ 10 ਅਕਤੂਬਰ 2024 ਤੋਂ 15 ਜਨਵਰੀ 2025 ਤੱਕ ਦੇ ਸਮੇਂ ਨੂੰ ਕਵਰ ਕਰਦਾ ਹੈ।
ਗੈਰ-ਰਜਿਸਟਰਡ ਕਿਸ ਨੂੰ ਮੰਨਿਆ ਜਾਂਦਾ ਹੈ
ਕੇਂਦਰੀ GST ਐਕਟ ਦੀ ਧਾਰਾ 22 ਮੁਤਾਬਕ ਕਿਸੇ ਸਪਲਾਇਰ ਨੂੰ ਉਦੋਂ ਰਜਿਸਟ੍ਰੇਸ਼ਨ ਕਰਾਉਣੀ ਪੈਂਦੀ ਹੈ ਜਦੋਂ ਇੱਕ ਵਿੱਤੀ ਸਾਲ ਵਿੱਚ ਉਸ ਦਾ ਕੁੱਲ ਟਰਨਓਵਰ ₹20 ਲੱਖ ਤੋਂ ਵੱਧ ਹੋ ਜਾਵੇ। ₹10 ਲੱਖ ਦੀ ਘੱਟ ਹੱਦ ਸਿਰਫ਼ ਵਿਸ਼ੇਸ਼ ਸ਼੍ਰੇਣੀ ਦੇ ਸੂਬਿਆਂ ਵਿੱਚ ਲਾਗੂ ਹੁੰਦੀ ਹੈ, ਅਤੇ ਪੰਜਾਬ ਉਨ੍ਹਾਂ ਵਿੱਚ ਸ਼ਾਮਲ ਨਹੀਂ। ਹੱਦ ਤੋਂ ਹੇਠਾਂ ਵਾਲਾ ਕੋਈ ਮਾਲਕ, ਜਿਸ ਨੇ ਆਪਣੀ ਮਰਜ਼ੀ ਨਾਲ ਰਜਿਸਟ੍ਰੇਸ਼ਨ ਨਹੀਂ ਕਰਾਈ, ਗੈਰ-ਰਜਿਸਟਰਡ ਸਪਲਾਇਰ ਹੈ, ਅਤੇ ਇੱਥੋਂ ਹੀ ਰਿਵਰਸ ਚਾਰਜ ਲਾਗੂ ਹੁੰਦਾ ਹੈ।
ਧਿਆਨ ਦੇਣ ਵਾਲੀਆਂ ਗੱਲਾਂ
1. ਦੱਸਿਆ ਗਿਆ ਕਿਰਾਇਆ ਪੂਰੀ ਲਾਗਤ ਨਹੀਂ। ਗੈਰ-ਰਜਿਸਟਰਡ ਮਾਲਕ ਤੋਂ ਕਿਰਾਏ 'ਤੇ ਲੈਣ ਵਾਲੇ ਰਜਿਸਟਰਡ ਕਿਰਾਏਦਾਰ ਲਈ ₹1 ਲੱਖ ਦੇ ਮਹੀਨਾਵਾਰ ਕਿਰਾਏ 'ਤੇ ₹18,000 ਦਾ GST ਬਣਦਾ ਹੈ, ਜੋ ਕਿਰਾਏਦਾਰ ਭਰਦਾ ਹੈ।
2. ਸਭ ਕੁਝ ਮਾਲਕ ਦੀ ਰਜਿਸਟ੍ਰੇਸ਼ਨ 'ਤੇ ਟਿਕਿਆ ਹੈ। ਲੀਜ਼ ਜਾਂ ਕਿਰਾਏ ਦੇ ਬਿੱਲ 'ਤੇ GST ਨੰਬਰ ਦੱਸਦਾ ਹੈ ਕਿ ਮਕਾਨ ਮਾਲਕ ਟੈਕਸ ਲਾਉਂਦਾ ਹੈ; ਉਸ ਦਾ ਨਾ ਹੋਣਾ ਰਜਿਸਟਰਡ ਕਿਰਾਏਦਾਰ ਲਈ ਰਿਵਰਸ ਚਾਰਜ ਵੱਲ ਇਸ਼ਾਰਾ ਕਰਦਾ ਹੈ।
3. ਕਿਸੇ ਕਾਰੋਬਾਰ ਵੱਲੋਂ ਲਿਆ ਫਲੈਟ ਐਂਟਰੀ 5AB ਵਿੱਚ ਨਹੀਂ ਆਉਂਦਾ। ਪਰ ਦਸੰਬਰ 2022 ਦੀ ਛੋਟ ਸਿਰਫ਼ ਉਸ ਰਜਿਸਟਰਡ ਵਿਅਕਤੀ 'ਤੇ ਲਾਗੂ ਹੁੰਦੀ ਹੈ ਜੋ ਘਰ ਨਿੱਜੀ ਹੈਸੀਅਤ ਵਿੱਚ ਆਪਣੀ ਰਿਹਾਇਸ਼ ਲਈ ਕਿਰਾਏ 'ਤੇ ਲੈਂਦਾ ਹੈ।
4. ਜ਼ਮੀਨ ਅਤੇ ਫੈਕਟਰੀ ਸ਼ੈੱਡਾਂ ਬਾਰੇ ਸਵਾਲ ਉੱਠਦੇ ਹਨ। EY ਦੇ 14 ਅਕਤੂਬਰ 2024 ਦੇ ਟੈਕਸ ਅਲਰਟ ਵਿੱਚ ਕਿਹਾ ਗਿਆ ਕਿ ਨੋਟੀਫਿਕੇਸ਼ਨ ਕੌਂਸਲ ਦੀ ਸ਼ਬਦਾਵਲੀ ਤੋਂ ਵਿਆਪਕ ਹੈ, ਜਿਸ ਵਿੱਚ ਸਿਰਫ਼ ਵਪਾਰਕ ਜਾਇਦਾਦ ਦੀ ਗੱਲ ਸੀ, ਅਤੇ ਕਰਦਾਤਾਵਾਂ ਨੂੰ ਇਹ ਤੈਅ ਕਰਨਾ ਪੈ ਸਕਦਾ ਹੈ ਕਿ ਉਦਯੋਗਿਕ ਪਲਾਟ, ਫੈਕਟਰੀ ਇਮਾਰਤਾਂ ਜਾਂ ਵਪਾਰਕ ਜ਼ਮੀਨ ਦੀ ਲੀਜ਼ ਇਸ ਦੇ ਦਾਇਰੇ ਵਿੱਚ ਆਉਂਦੀ ਹੈ ਜਾਂ ਨਹੀਂ।
ਸਬੰਧਤ ਲੇਖ
- Mohali Tenancy Rules Under the Punjab Rent Act
- Mohali Shops With Under 20 Workers Need Only an Intimation
- Mohali Flats Bought After Completion Carry No GST
ਸਰੋਤ: ਅਸੀਂ ਜਿਨ੍ਹਾਂ ਸਰੋਤਾਂ ਦੀ ਵਰਤੋਂ ਕਰਦੇ ਹਾਂ, ਉਹ ਸਾਡੇ Editorial Sources ਪੰਨੇ 'ਤੇ ਦਿੱਤੇ ਗਏ ਹਨ।
ਇਹ ਲੇਖ ਦੱਸਦਾ ਹੈ ਕਿ ਮੋਹਾਲੀ ਅਤੇ ਟ੍ਰਾਈਸਿਟੀ ਵਿੱਚ ਦੁਕਾਨਾਂ, ਦਫ਼ਤਰਾਂ ਅਤੇ ਹੋਰ ਥਾਵਾਂ ਦੇ ਕਿਰਾਏ 'ਤੇ GST ਕਿਵੇਂ ਲਾਗੂ ਹੁੰਦਾ ਹੈ, ਅਤੇ 17 ਨਵੰਬਰ 2026 ਨੂੰ ਪੜ੍ਹੇ ਗਏ ਸਰੋਤਾਂ 'ਤੇ ਆਧਾਰਿਤ ਹੈ। ਇਹ ਆਮ ਜਾਣਕਾਰੀ ਹੈ, ਟੈਕਸ, ਕਾਨੂੰਨੀ ਜਾਂ ਕਾਰੋਬਾਰੀ ਸਲਾਹ ਨਹੀਂ।