
Since 6 April 2025, UK inheritance tax no longer turns on domicile. It turns on years of residence. A person who has been UK resident for at least 10 of the 20 tax years before a death or a gift is a long-term UK resident, and HM Revenue and Customs (HMRC) charges inheritance tax on overseas assets that person owns outright. A flat, house or plot in Mohali, Zirakpur or Kharar is such an asset.
The rate is 40% on the part of an estate above the £325,000 nil rate band. One older rule can keep a Mohali home outside the UK charge on death: a 1956 agreement between the UK and India, which HMRC still applies to people whose domicile is India. The question exists only because the owner lives in the UK. India has had no estate duty since it was abolished in 1985, so an owner living in India faces no inheritance tax on the same home.
Who counts as a long-term UK resident
- Test: UK resident in at least 10 of the 20 tax years immediately before the tax year of the death or gift
- How residence is decided: as for UK income tax and capital gains tax, under the Statutory Residence Test from 2013-14
- Split years: a year split under the Statutory Residence Test counts as a full year
- Start date: deaths and gifts on or after 6 April 2025; earlier ones stay under the old domicile rules
- Reset: a person who returns after 10 consecutive years outside the UK starts the count again from the year of return
What the UK charges
- Rate: 40% on the value above the threshold
- Nil rate band: £325,000, set until 5 April 2031 in HMRC's published thresholds
- Gifts during life: tax can fall on them where more than £325,000 is given away and the giver dies within seven years
For a long-term UK resident, the Mohali home is valued with the UK home, savings and other assets as part of one estate.
Leaving the UK does not end it at once
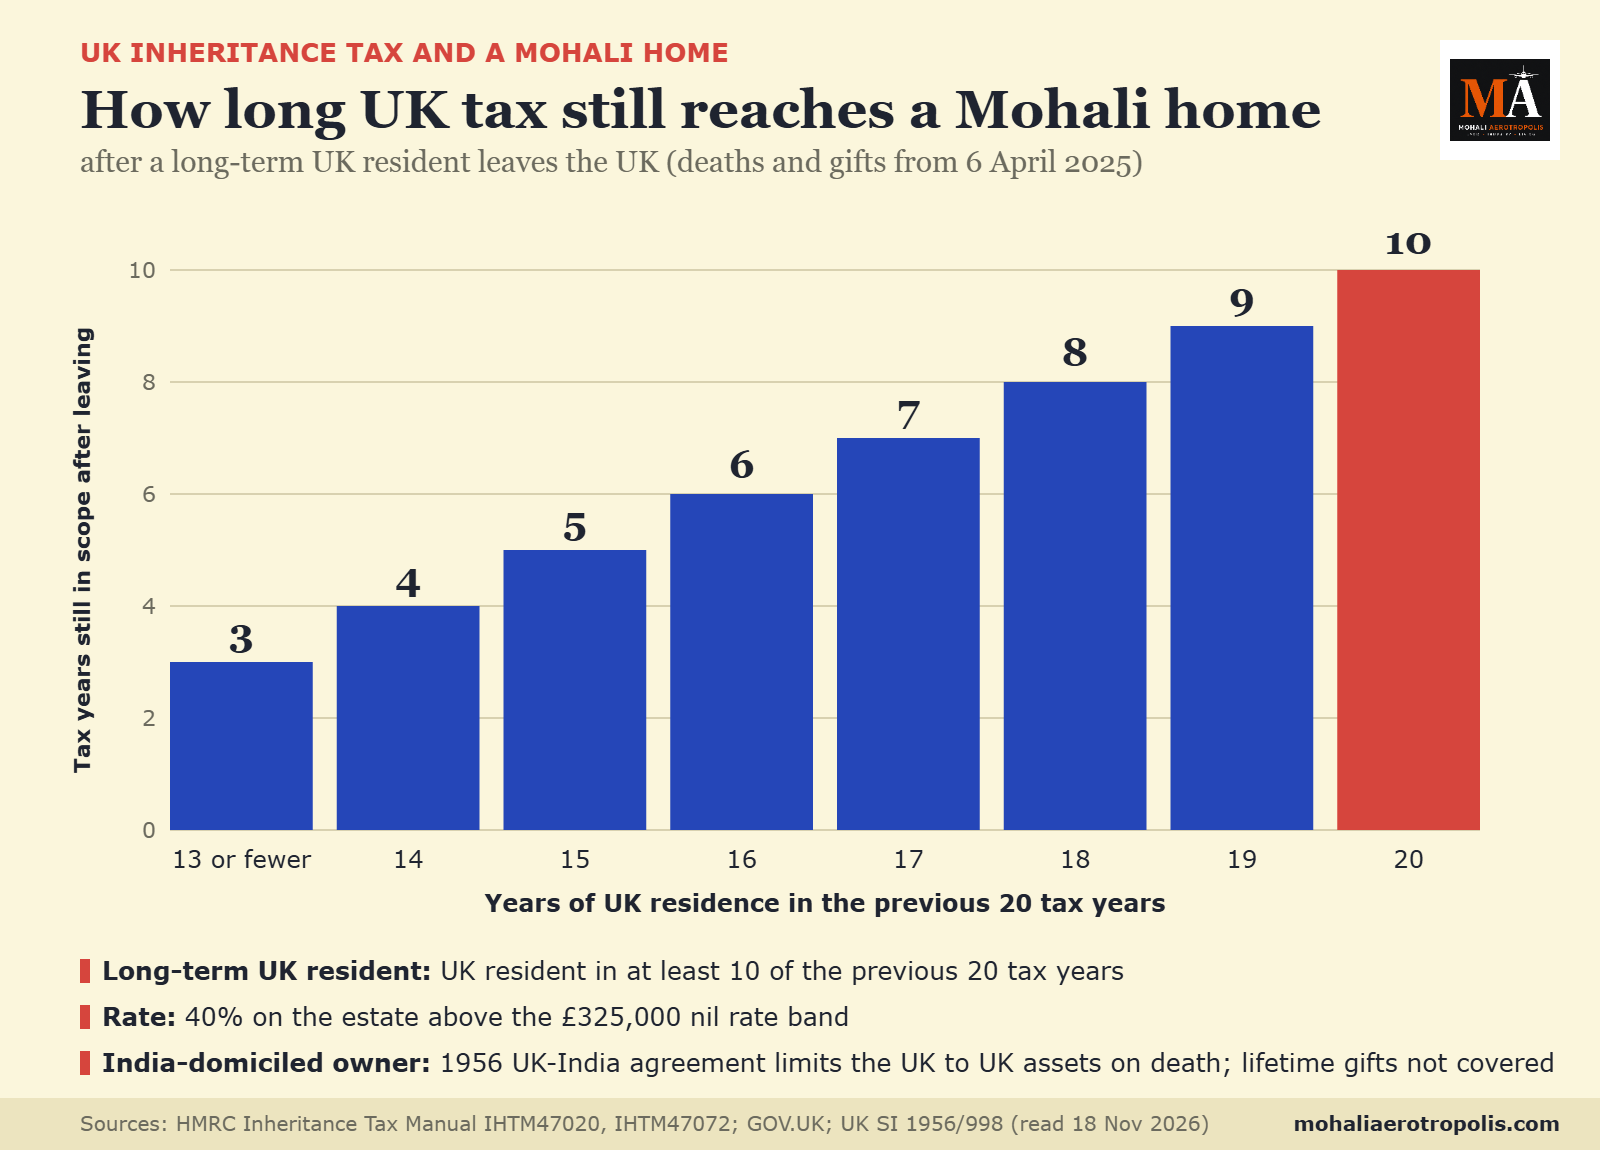
A long-term resident who leaves stays within UK inheritance tax on overseas assets for a number of tax years. HMRC's manual ties the length to the years of UK residence in the previous 20:
- 13 years or fewer: three tax years after leaving
- 14 years: four tax years
- 15 years: five tax years
- 16 years: six tax years
- 17 years: seven tax years
- 18 years: eight tax years
- 19 years: nine tax years
- 20 years: 10 tax years
An owner who retires from the UK to Mohali after 20 years of UK residence therefore keeps the Mohali home within UK inheritance tax for 10 tax years after leaving.
The 1956 UK-India agreement
The Double Taxation Relief (Estate Duty) (India) Order 1956 gives effect to an agreement signed in New Delhi on 3 April 1956. Its rules place immovable property in the country where it lies, so a Mohali flat or plot is Indian property under it.
HMRC's Inheritance Tax Manual (page IHTM47072, updated 7 April 2026) lists it among four agreements made before 1975, with France, Italy, India and Pakistan, that keep working on domicile after the 2025 change. Three points on that page decide how far it reaches:
1. It works on common law domicile, not on the 10-year residence count and not on the old "deemed domicile".
2. For a person whose common law domicile is India, the UK's taxing rights are restricted to the UK assets in the estate. A Mohali home then stays outside UK inheritance tax on death.
3. It covers only taxes charged on death. A lifetime gift of a Mohali home by a long-term UK resident, for example to a son or daughter by gift deed, gets no protection from it.
Points to weigh
- The protection depends on domicile still being Indian. An owner whose common law domicile has become British falls under the long-term residence test like any other UK resident.
- Gifts made during life sit outside the 1956 agreement, so the seven-year rule can apply to a Mohali home given away by a long-term UK resident.
- HMRC's 2025 guidance treats overseas property held in a trust under separate rules, including property placed in a trust while the owner was not a long-term resident.
- No inheritance tax arises in India, but an heir abroad still has to move the home into their own name, which takes documents signed and attested overseas. India's foreign exchange rules on what an heir abroad may inherit apply as well.
Related reading
- Mohali home sold from the UK and the tax on the sterling gain
- Mohali rent faces higher UK tax from April 2027
- When a GMADA allottee dies and the heir lives abroad
- Inheriting a Mohali property while living abroad
Sources: The sources we use are listed on our Editorial Sources page.
This article explains published rules and is not tax, legal or financial advice. HMRC's guidance on inheritance tax for long-term UK residents (published 6 April 2025), the HMRC Inheritance Tax Manual pages IHTM47001, IHTM47020 and IHTM47072 (updated 7 April 2026), the GOV.UK inheritance tax page and thresholds table, and the Double Taxation Relief (Estate Duty) (India) Order 1956 on legislation.gov.uk were read on 18 November 2026. UK and Indian rules change; a qualified adviser in each country can apply them to a particular estate.
6 अप्रैल 2025 से UK का inheritance tax अब domicile पर नहीं टिका है। अब यह निवास के वर्षों पर टिका है। जो व्यक्ति किसी मृत्यु या उपहार से पहले के 20 टैक्स वर्षों में से कम से कम 10 वर्ष UK का निवासी रहा हो, वह long-term UK resident है, और HM Revenue and Customs (HMRC) उस व्यक्ति के पूर्ण स्वामित्व वाली विदेशी संपत्तियों पर inheritance tax लगाता है। मोहाली, ज़ीरकपुर या खरड़ में फ्लैट, मकान या प्लॉट ऐसी ही संपत्ति है।
दर £325,000 के nil rate band से ऊपर वाले हिस्से पर 40% है। एक पुराना नियम मृत्यु पर मोहाली के मकान को UK टैक्स से बाहर रख सकता है: UK और भारत के बीच 1956 का समझौता, जिसे HMRC अब भी उन लोगों पर लागू करता है जिनका domicile भारत है। यह सवाल केवल इसलिए उठता है क्योंकि मालिक UK में रहता है। भारत में 1985 में estate duty खत्म होने के बाद से ऐसा कोई टैक्स नहीं है, इसलिए भारत में रहने वाले मालिक पर उसी मकान के लिए कोई inheritance tax नहीं लगता।
long-term UK resident कौन माना जाता है
- कसौटी: मृत्यु या उपहार वाले टैक्स वर्ष से ठीक पहले के 20 टैक्स वर्षों में से कम से कम 10 में UK निवासी
- निवास कैसे तय होता है: UK आयकर और capital gains tax की तरह, 2013-14 से Statutory Residence Test के तहत
- बंटे हुए वर्ष: Statutory Residence Test के तहत बंटा हुआ वर्ष पूरा वर्ष गिना जाता है
- शुरुआत: 6 अप्रैल 2025 या उसके बाद की मृत्यु और उपहार; उससे पहले वाले पुराने domicile नियमों के तहत रहते हैं
- दोबारा गिनती: जो व्यक्ति लगातार 10 वर्ष UK से बाहर रहकर लौटता है, उसकी गिनती लौटने के वर्ष से फिर शुरू होती है
UK कितना टैक्स लेता है
- दर: सीमा से ऊपर के मूल्य पर 40%
- Nil rate band: £325,000, HMRC की प्रकाशित सीमाओं में 5 अप्रैल 2031 तक तय
- जीवनकाल में दिए उपहार: अगर £325,000 से अधिक दिया जाए और देने वाले की मृत्यु सात वर्ष के भीतर हो, तो उन पर टैक्स लग सकता है
long-term UK resident के लिए मोहाली का मकान UK के मकान, बचत और अन्य संपत्तियों के साथ एक ही estate के हिस्से के रूप में आंका जाता है।
UK छोड़ते ही यह खत्म नहीं होता
UK छोड़ने वाला long-term resident कुछ टैक्स वर्षों तक विदेशी संपत्तियों पर UK inheritance tax के दायरे में रहता है। HMRC का manual इसकी अवधि पिछले 20 वर्षों में UK निवास के वर्षों से जोड़ता है:
- 13 वर्ष या कम: छोड़ने के बाद तीन टैक्स वर्ष
- 14 वर्ष: चार टैक्स वर्ष
- 15 वर्ष: पांच टैक्स वर्ष
- 16 वर्ष: छह टैक्स वर्ष
- 17 वर्ष: सात टैक्स वर्ष
- 18 वर्ष: आठ टैक्स वर्ष
- 19 वर्ष: नौ टैक्स वर्ष
- 20 वर्ष: 10 टैक्स वर्ष
इसलिए UK में 20 वर्ष रहने के बाद मोहाली लौटकर बसने वाले मालिक का मोहाली मकान छोड़ने के बाद 10 टैक्स वर्षों तक UK inheritance tax के दायरे में रहता है।
1956 का UK-भारत समझौता
Double Taxation Relief (Estate Duty) (India) Order 1956 उस समझौते को लागू करता है जिस पर 3 अप्रैल 1956 को नई दिल्ली में हस्ताक्षर हुए थे। इसके नियम अचल संपत्ति को उसी देश की मानते हैं जहां वह स्थित है, इसलिए इसके तहत मोहाली का फ्लैट या प्लॉट भारतीय संपत्ति है।
HMRC का Inheritance Tax Manual (पेज IHTM47072, अपडेट 7 अप्रैल 2026) इसे 1975 से पहले के उन चार समझौतों में गिनता है, फ्रांस, इटली, भारत और पाकिस्तान के साथ, जो 2025 के बदलाव के बाद भी domicile पर चलते हैं। उस पेज की तीन बातें तय करती हैं कि इसकी पहुंच कितनी है:
1. यह common law domicile पर चलता है, 10 वर्ष की निवास गिनती पर नहीं और पुराने "deemed domicile" पर भी नहीं।
2. जिस व्यक्ति का common law domicile भारत है, उसके लिए UK के टैक्स अधिकार estate की UK संपत्तियों तक सीमित हैं। तब मृत्यु पर मोहाली का मकान UK inheritance tax से बाहर रहता है।
3. यह केवल मृत्यु पर लगने वाले टैक्स पर लागू होता है। long-term UK resident द्वारा जीवनकाल में मोहाली मकान का उपहार, जैसे gift deed से बेटे या बेटी को, इससे कोई सुरक्षा नहीं पाता।
ध्यान देने योग्य बातें
- यह सुरक्षा domicile के भारतीय बने रहने पर निर्भर है। जिस मालिक का common law domicile ब्रिटिश हो गया है, वह किसी भी अन्य UK निवासी की तरह long-term residence test के तहत आता है।
- जीवनकाल में दिए उपहार 1956 के समझौते से बाहर हैं, इसलिए long-term UK resident द्वारा उपहार में दिए मोहाली मकान पर सात वर्ष का नियम लागू हो सकता है।
- HMRC की 2025 की guidance trust में रखी विदेशी संपत्ति को अलग नियमों से देखती है, जिसमें वह संपत्ति भी शामिल है जो मालिक के long-term resident न होने के समय trust में रखी गई थी।
- भारत में कोई inheritance tax नहीं लगता, लेकिन विदेश में रहने वाले वारिस को मकान अपने नाम कराना पड़ता है, जिसके लिए विदेश में हस्ताक्षरित और सत्यापित दस्तावेज़ चाहिए। विदेश में रहने वाला वारिस क्या विरासत में ले सकता है, इस पर भारत के विदेशी मुद्रा नियम भी लागू होते हैं।
संबंधित लेख
- UK से बेचे गए मोहाली मकान और स्टर्लिंग लाभ पर टैक्स
- अप्रैल 2027 से मोहाली किराए पर UK में ज़्यादा टैक्स
- GMADA आवंटी की मृत्यु और विदेश में रहने वाला वारिस
- विदेश में रहते हुए मोहाली संपत्ति विरासत में पाना
स्रोत: हम जिन स्रोतों का उपयोग करते हैं, वे हमारे Editorial Sources पेज पर सूचीबद्ध हैं।
यह लेख प्रकाशित नियमों की व्याख्या करता है और टैक्स, कानूनी या वित्तीय सलाह नहीं है। long-term UK residents के लिए inheritance tax पर HMRC की guidance (प्रकाशित 6 अप्रैल 2025), HMRC Inheritance Tax Manual के पेज IHTM47001, IHTM47020 और IHTM47072 (अपडेट 7 अप्रैल 2026), GOV.UK का inheritance tax पेज और सीमाओं की तालिका, तथा legislation.gov.uk पर Double Taxation Relief (Estate Duty) (India) Order 1956 को 18 नवंबर 2026 को पढ़ा गया। UK और भारतीय नियम बदलते रहते हैं; किसी खास estate पर उन्हें दोनों देशों के योग्य सलाहकार लागू कर सकते हैं।
6 ਅਪ੍ਰੈਲ 2025 ਤੋਂ UK ਦਾ inheritance tax ਹੁਣ domicile ਉੱਤੇ ਨਹੀਂ ਟਿਕਿਆ। ਹੁਣ ਇਹ ਰਿਹਾਇਸ਼ ਦੇ ਸਾਲਾਂ ਉੱਤੇ ਟਿਕਿਆ ਹੈ। ਜੋ ਵਿਅਕਤੀ ਕਿਸੇ ਮੌਤ ਜਾਂ ਤੋਹਫ਼ੇ ਤੋਂ ਪਹਿਲਾਂ ਦੇ 20 ਟੈਕਸ ਸਾਲਾਂ ਵਿੱਚੋਂ ਘੱਟੋ-ਘੱਟ 10 ਸਾਲ UK ਦਾ ਨਿਵਾਸੀ ਰਿਹਾ ਹੋਵੇ, ਉਹ long-term UK resident ਹੈ, ਅਤੇ HM Revenue and Customs (HMRC) ਉਸ ਵਿਅਕਤੀ ਦੀ ਪੂਰੀ ਮਾਲਕੀ ਵਾਲੀਆਂ ਵਿਦੇਸ਼ੀ ਜਾਇਦਾਦਾਂ ਉੱਤੇ inheritance tax ਲਾਉਂਦਾ ਹੈ। ਮੋਹਾਲੀ, ਜ਼ੀਰਕਪੁਰ ਜਾਂ ਖਰੜ ਵਿੱਚ ਫਲੈਟ, ਮਕਾਨ ਜਾਂ ਪਲਾਟ ਅਜਿਹੀ ਹੀ ਜਾਇਦਾਦ ਹੈ।
ਦਰ £325,000 ਦੇ nil rate band ਤੋਂ ਉੱਪਰ ਵਾਲੇ ਹਿੱਸੇ ਉੱਤੇ 40% ਹੈ। ਇੱਕ ਪੁਰਾਣਾ ਨਿਯਮ ਮੌਤ ਉੱਤੇ ਮੋਹਾਲੀ ਦੇ ਮਕਾਨ ਨੂੰ UK ਟੈਕਸ ਤੋਂ ਬਾਹਰ ਰੱਖ ਸਕਦਾ ਹੈ: UK ਅਤੇ ਭਾਰਤ ਵਿਚਾਲੇ 1956 ਦਾ ਸਮਝੌਤਾ, ਜਿਸ ਨੂੰ HMRC ਅਜੇ ਵੀ ਉਨ੍ਹਾਂ ਲੋਕਾਂ ਉੱਤੇ ਲਾਗੂ ਕਰਦਾ ਹੈ ਜਿਨ੍ਹਾਂ ਦਾ domicile ਭਾਰਤ ਹੈ। ਇਹ ਸਵਾਲ ਸਿਰਫ਼ ਇਸ ਲਈ ਉੱਠਦਾ ਹੈ ਕਿਉਂਕਿ ਮਾਲਕ UK ਵਿੱਚ ਰਹਿੰਦਾ ਹੈ। ਭਾਰਤ ਵਿੱਚ 1985 ਵਿੱਚ estate duty ਖ਼ਤਮ ਹੋਣ ਤੋਂ ਬਾਅਦ ਅਜਿਹਾ ਕੋਈ ਟੈਕਸ ਨਹੀਂ, ਇਸ ਲਈ ਭਾਰਤ ਵਿੱਚ ਰਹਿਣ ਵਾਲੇ ਮਾਲਕ ਉੱਤੇ ਉਸੇ ਮਕਾਨ ਲਈ ਕੋਈ inheritance tax ਨਹੀਂ ਲੱਗਦਾ।
long-term UK resident ਕੌਣ ਮੰਨਿਆ ਜਾਂਦਾ ਹੈ
- ਕਸੌਟੀ: ਮੌਤ ਜਾਂ ਤੋਹਫ਼ੇ ਵਾਲੇ ਟੈਕਸ ਸਾਲ ਤੋਂ ਠੀਕ ਪਹਿਲਾਂ ਦੇ 20 ਟੈਕਸ ਸਾਲਾਂ ਵਿੱਚੋਂ ਘੱਟੋ-ਘੱਟ 10 ਵਿੱਚ UK ਨਿਵਾਸੀ
- ਰਿਹਾਇਸ਼ ਕਿਵੇਂ ਤੈਅ ਹੁੰਦੀ ਹੈ: UK ਆਮਦਨ ਕਰ ਅਤੇ capital gains tax ਵਾਂਗ, 2013-14 ਤੋਂ Statutory Residence Test ਹੇਠ
- ਵੰਡੇ ਹੋਏ ਸਾਲ: Statutory Residence Test ਹੇਠ ਵੰਡਿਆ ਸਾਲ ਪੂਰਾ ਸਾਲ ਗਿਣਿਆ ਜਾਂਦਾ ਹੈ
- ਸ਼ੁਰੂਆਤ: 6 ਅਪ੍ਰੈਲ 2025 ਜਾਂ ਉਸ ਤੋਂ ਬਾਅਦ ਦੀਆਂ ਮੌਤਾਂ ਅਤੇ ਤੋਹਫ਼ੇ; ਉਸ ਤੋਂ ਪਹਿਲਾਂ ਵਾਲੇ ਪੁਰਾਣੇ domicile ਨਿਯਮਾਂ ਹੇਠ ਰਹਿੰਦੇ ਹਨ
- ਮੁੜ ਗਿਣਤੀ: ਜੋ ਵਿਅਕਤੀ ਲਗਾਤਾਰ 10 ਸਾਲ UK ਤੋਂ ਬਾਹਰ ਰਹਿ ਕੇ ਵਾਪਸ ਆਉਂਦਾ ਹੈ, ਉਸ ਦੀ ਗਿਣਤੀ ਵਾਪਸੀ ਦੇ ਸਾਲ ਤੋਂ ਮੁੜ ਸ਼ੁਰੂ ਹੁੰਦੀ ਹੈ
UK ਕਿੰਨਾ ਟੈਕਸ ਲੈਂਦਾ ਹੈ
- ਦਰ: ਹੱਦ ਤੋਂ ਉੱਪਰ ਦੇ ਮੁੱਲ ਉੱਤੇ 40%
- Nil rate band: £325,000, HMRC ਦੀਆਂ ਪ੍ਰਕਾਸ਼ਿਤ ਹੱਦਾਂ ਵਿੱਚ 5 ਅਪ੍ਰੈਲ 2031 ਤੱਕ ਤੈਅ
- ਜਿਊਂਦੇ ਜੀਅ ਦਿੱਤੇ ਤੋਹਫ਼ੇ: ਜੇ £325,000 ਤੋਂ ਵੱਧ ਦਿੱਤਾ ਜਾਵੇ ਅਤੇ ਦੇਣ ਵਾਲੇ ਦੀ ਮੌਤ ਸੱਤ ਸਾਲਾਂ ਦੇ ਅੰਦਰ ਹੋਵੇ, ਤਾਂ ਉਨ੍ਹਾਂ ਉੱਤੇ ਟੈਕਸ ਲੱਗ ਸਕਦਾ ਹੈ
long-term UK resident ਲਈ ਮੋਹਾਲੀ ਦਾ ਮਕਾਨ UK ਦੇ ਮਕਾਨ, ਬੱਚਤ ਅਤੇ ਹੋਰ ਜਾਇਦਾਦਾਂ ਨਾਲ ਇੱਕੋ estate ਦੇ ਹਿੱਸੇ ਵਜੋਂ ਆਂਕਿਆ ਜਾਂਦਾ ਹੈ।
UK ਛੱਡਦਿਆਂ ਹੀ ਇਹ ਖ਼ਤਮ ਨਹੀਂ ਹੁੰਦਾ
UK ਛੱਡਣ ਵਾਲਾ long-term resident ਕੁਝ ਟੈਕਸ ਸਾਲਾਂ ਤੱਕ ਵਿਦੇਸ਼ੀ ਜਾਇਦਾਦਾਂ ਉੱਤੇ UK inheritance tax ਦੇ ਦਾਇਰੇ ਵਿੱਚ ਰਹਿੰਦਾ ਹੈ। HMRC ਦਾ manual ਇਸ ਦੀ ਮਿਆਦ ਪਿਛਲੇ 20 ਸਾਲਾਂ ਵਿੱਚ UK ਰਿਹਾਇਸ਼ ਦੇ ਸਾਲਾਂ ਨਾਲ ਜੋੜਦਾ ਹੈ:
- 13 ਸਾਲ ਜਾਂ ਘੱਟ: ਛੱਡਣ ਤੋਂ ਬਾਅਦ ਤਿੰਨ ਟੈਕਸ ਸਾਲ
- 14 ਸਾਲ: ਚਾਰ ਟੈਕਸ ਸਾਲ
- 15 ਸਾਲ: ਪੰਜ ਟੈਕਸ ਸਾਲ
- 16 ਸਾਲ: ਛੇ ਟੈਕਸ ਸਾਲ
- 17 ਸਾਲ: ਸੱਤ ਟੈਕਸ ਸਾਲ
- 18 ਸਾਲ: ਅੱਠ ਟੈਕਸ ਸਾਲ
- 19 ਸਾਲ: ਨੌਂ ਟੈਕਸ ਸਾਲ
- 20 ਸਾਲ: 10 ਟੈਕਸ ਸਾਲ
ਇਸ ਲਈ UK ਵਿੱਚ 20 ਸਾਲ ਰਹਿਣ ਤੋਂ ਬਾਅਦ ਮੋਹਾਲੀ ਆ ਕੇ ਵਸਣ ਵਾਲੇ ਮਾਲਕ ਦਾ ਮੋਹਾਲੀ ਮਕਾਨ ਛੱਡਣ ਤੋਂ ਬਾਅਦ 10 ਟੈਕਸ ਸਾਲਾਂ ਤੱਕ UK inheritance tax ਦੇ ਦਾਇਰੇ ਵਿੱਚ ਰਹਿੰਦਾ ਹੈ।
1956 ਦਾ UK-ਭਾਰਤ ਸਮਝੌਤਾ
Double Taxation Relief (Estate Duty) (India) Order 1956 ਉਸ ਸਮਝੌਤੇ ਨੂੰ ਲਾਗੂ ਕਰਦਾ ਹੈ ਜਿਸ ਉੱਤੇ 3 ਅਪ੍ਰੈਲ 1956 ਨੂੰ ਨਵੀਂ ਦਿੱਲੀ ਵਿੱਚ ਦਸਤਖ਼ਤ ਹੋਏ ਸਨ। ਇਸ ਦੇ ਨਿਯਮ ਅਚੱਲ ਜਾਇਦਾਦ ਨੂੰ ਉਸੇ ਦੇਸ਼ ਦੀ ਮੰਨਦੇ ਹਨ ਜਿੱਥੇ ਉਹ ਸਥਿਤ ਹੈ, ਇਸ ਲਈ ਇਸ ਹੇਠ ਮੋਹਾਲੀ ਦਾ ਫਲੈਟ ਜਾਂ ਪਲਾਟ ਭਾਰਤੀ ਜਾਇਦਾਦ ਹੈ।
HMRC ਦਾ Inheritance Tax Manual (ਪੰਨਾ IHTM47072, ਅਪਡੇਟ 7 ਅਪ੍ਰੈਲ 2026) ਇਸ ਨੂੰ 1975 ਤੋਂ ਪਹਿਲਾਂ ਦੇ ਉਨ੍ਹਾਂ ਚਾਰ ਸਮਝੌਤਿਆਂ ਵਿੱਚ ਗਿਣਦਾ ਹੈ, ਫਰਾਂਸ, ਇਟਲੀ, ਭਾਰਤ ਅਤੇ ਪਾਕਿਸਤਾਨ ਨਾਲ, ਜੋ 2025 ਦੀ ਤਬਦੀਲੀ ਤੋਂ ਬਾਅਦ ਵੀ domicile ਉੱਤੇ ਚੱਲਦੇ ਹਨ। ਉਸ ਪੰਨੇ ਦੀਆਂ ਤਿੰਨ ਗੱਲਾਂ ਤੈਅ ਕਰਦੀਆਂ ਹਨ ਕਿ ਇਸ ਦੀ ਪਹੁੰਚ ਕਿੰਨੀ ਹੈ:
1. ਇਹ common law domicile ਉੱਤੇ ਚੱਲਦਾ ਹੈ, 10 ਸਾਲ ਦੀ ਰਿਹਾਇਸ਼ੀ ਗਿਣਤੀ ਉੱਤੇ ਨਹੀਂ ਅਤੇ ਪੁਰਾਣੇ "deemed domicile" ਉੱਤੇ ਵੀ ਨਹੀਂ।
2. ਜਿਸ ਵਿਅਕਤੀ ਦਾ common law domicile ਭਾਰਤ ਹੈ, ਉਸ ਲਈ UK ਦੇ ਟੈਕਸ ਅਧਿਕਾਰ estate ਦੀਆਂ UK ਜਾਇਦਾਦਾਂ ਤੱਕ ਸੀਮਤ ਹਨ। ਤਦ ਮੌਤ ਉੱਤੇ ਮੋਹਾਲੀ ਦਾ ਮਕਾਨ UK inheritance tax ਤੋਂ ਬਾਹਰ ਰਹਿੰਦਾ ਹੈ।
3. ਇਹ ਸਿਰਫ਼ ਮੌਤ ਉੱਤੇ ਲੱਗਣ ਵਾਲੇ ਟੈਕਸ ਉੱਤੇ ਲਾਗੂ ਹੁੰਦਾ ਹੈ। long-term UK resident ਵੱਲੋਂ ਜਿਊਂਦੇ ਜੀਅ ਮੋਹਾਲੀ ਮਕਾਨ ਦਾ ਤੋਹਫ਼ਾ, ਜਿਵੇਂ gift deed ਰਾਹੀਂ ਪੁੱਤਰ ਜਾਂ ਧੀ ਨੂੰ, ਇਸ ਤੋਂ ਕੋਈ ਸੁਰੱਖਿਆ ਨਹੀਂ ਲੈਂਦਾ।
ਧਿਆਨ ਦੇਣ ਯੋਗ ਗੱਲਾਂ
- ਇਹ ਸੁਰੱਖਿਆ domicile ਦੇ ਭਾਰਤੀ ਬਣੇ ਰਹਿਣ ਉੱਤੇ ਨਿਰਭਰ ਹੈ। ਜਿਸ ਮਾਲਕ ਦਾ common law domicile ਬ੍ਰਿਟਿਸ਼ ਹੋ ਗਿਆ ਹੈ, ਉਹ ਕਿਸੇ ਵੀ ਹੋਰ UK ਨਿਵਾਸੀ ਵਾਂਗ long-term residence test ਹੇਠ ਆਉਂਦਾ ਹੈ।
- ਜਿਊਂਦੇ ਜੀਅ ਦਿੱਤੇ ਤੋਹਫ਼ੇ 1956 ਦੇ ਸਮਝੌਤੇ ਤੋਂ ਬਾਹਰ ਹਨ, ਇਸ ਲਈ long-term UK resident ਵੱਲੋਂ ਤੋਹਫ਼ੇ ਵਿੱਚ ਦਿੱਤੇ ਮੋਹਾਲੀ ਮਕਾਨ ਉੱਤੇ ਸੱਤ ਸਾਲ ਦਾ ਨਿਯਮ ਲਾਗੂ ਹੋ ਸਕਦਾ ਹੈ।
- HMRC ਦੀ 2025 ਦੀ guidance trust ਵਿੱਚ ਰੱਖੀ ਵਿਦੇਸ਼ੀ ਜਾਇਦਾਦ ਨੂੰ ਵੱਖਰੇ ਨਿਯਮਾਂ ਨਾਲ ਵੇਖਦੀ ਹੈ, ਜਿਸ ਵਿੱਚ ਉਹ ਜਾਇਦਾਦ ਵੀ ਸ਼ਾਮਲ ਹੈ ਜੋ ਮਾਲਕ ਦੇ long-term resident ਨਾ ਹੋਣ ਵੇਲੇ trust ਵਿੱਚ ਰੱਖੀ ਗਈ ਸੀ।
- ਭਾਰਤ ਵਿੱਚ ਕੋਈ inheritance tax ਨਹੀਂ ਲੱਗਦਾ, ਪਰ ਵਿਦੇਸ਼ ਵਿੱਚ ਰਹਿਣ ਵਾਲੇ ਵਾਰਸ ਨੂੰ ਮਕਾਨ ਆਪਣੇ ਨਾਂ ਕਰਵਾਉਣਾ ਪੈਂਦਾ ਹੈ, ਜਿਸ ਲਈ ਵਿਦੇਸ਼ ਵਿੱਚ ਦਸਤਖ਼ਤ ਅਤੇ ਤਸਦੀਕ ਕੀਤੇ ਦਸਤਾਵੇਜ਼ ਚਾਹੀਦੇ ਹਨ। ਵਿਦੇਸ਼ ਵਿੱਚ ਰਹਿਣ ਵਾਲਾ ਵਾਰਸ ਕੀ ਵਿਰਾਸਤ ਵਿੱਚ ਲੈ ਸਕਦਾ ਹੈ, ਇਸ ਬਾਰੇ ਭਾਰਤ ਦੇ ਵਿਦੇਸ਼ੀ ਮੁਦਰਾ ਨਿਯਮ ਵੀ ਲਾਗੂ ਹੁੰਦੇ ਹਨ।
ਸੰਬੰਧਿਤ ਲੇਖ
- UK ਤੋਂ ਵੇਚੇ ਮੋਹਾਲੀ ਮਕਾਨ ਅਤੇ ਸਟਰਲਿੰਗ ਲਾਭ ਉੱਤੇ ਟੈਕਸ
- ਅਪ੍ਰੈਲ 2027 ਤੋਂ ਮੋਹਾਲੀ ਕਿਰਾਏ ਉੱਤੇ UK ਵਿੱਚ ਵੱਧ ਟੈਕਸ
- GMADA ਅਲਾਟੀ ਦੀ ਮੌਤ ਅਤੇ ਵਿਦੇਸ਼ ਵਿੱਚ ਰਹਿਣ ਵਾਲਾ ਵਾਰਸ
- ਵਿਦੇਸ਼ ਵਿੱਚ ਰਹਿੰਦਿਆਂ ਮੋਹਾਲੀ ਜਾਇਦਾਦ ਵਿਰਾਸਤ ਵਿੱਚ ਲੈਣਾ
ਸਰੋਤ: ਅਸੀਂ ਜਿਨ੍ਹਾਂ ਸਰੋਤਾਂ ਦੀ ਵਰਤੋਂ ਕਰਦੇ ਹਾਂ, ਉਹ ਸਾਡੇ Editorial Sources ਪੰਨੇ ਉੱਤੇ ਦਰਜ ਹਨ।
ਇਹ ਲੇਖ ਪ੍ਰਕਾਸ਼ਿਤ ਨਿਯਮਾਂ ਦੀ ਵਿਆਖਿਆ ਕਰਦਾ ਹੈ ਅਤੇ ਟੈਕਸ, ਕਾਨੂੰਨੀ ਜਾਂ ਵਿੱਤੀ ਸਲਾਹ ਨਹੀਂ ਹੈ। long-term UK residents ਲਈ inheritance tax ਬਾਰੇ HMRC ਦੀ guidance (ਪ੍ਰਕਾਸ਼ਿਤ 6 ਅਪ੍ਰੈਲ 2025), HMRC Inheritance Tax Manual ਦੇ ਪੰਨੇ IHTM47001, IHTM47020 ਅਤੇ IHTM47072 (ਅਪਡੇਟ 7 ਅਪ੍ਰੈਲ 2026), GOV.UK ਦਾ inheritance tax ਪੰਨਾ ਅਤੇ ਹੱਦਾਂ ਦੀ ਸਾਰਣੀ, ਅਤੇ legislation.gov.uk ਉੱਤੇ Double Taxation Relief (Estate Duty) (India) Order 1956 ਨੂੰ 18 ਨਵੰਬਰ 2026 ਨੂੰ ਪੜ੍ਹਿਆ ਗਿਆ। UK ਅਤੇ ਭਾਰਤੀ ਨਿਯਮ ਬਦਲਦੇ ਰਹਿੰਦੇ ਹਨ; ਕਿਸੇ ਖ਼ਾਸ estate ਉੱਤੇ ਉਨ੍ਹਾਂ ਨੂੰ ਦੋਵਾਂ ਦੇਸ਼ਾਂ ਦੇ ਯੋਗ ਸਲਾਹਕਾਰ ਲਾਗੂ ਕਰ ਸਕਦੇ ਹਨ।